A Oakville Mortgage Broker
Who Works for You, Not the Bank.
Buying in one of the priciest markets in the country. Renewing. Refinancing. Or self-employed, or carrying bruised credit, and tired of hearing no. Whatever brought you here, I shop 50+ lenders to find the one that fits instead of a checklist. Local to Halton, in your corner from the first call to closing day.
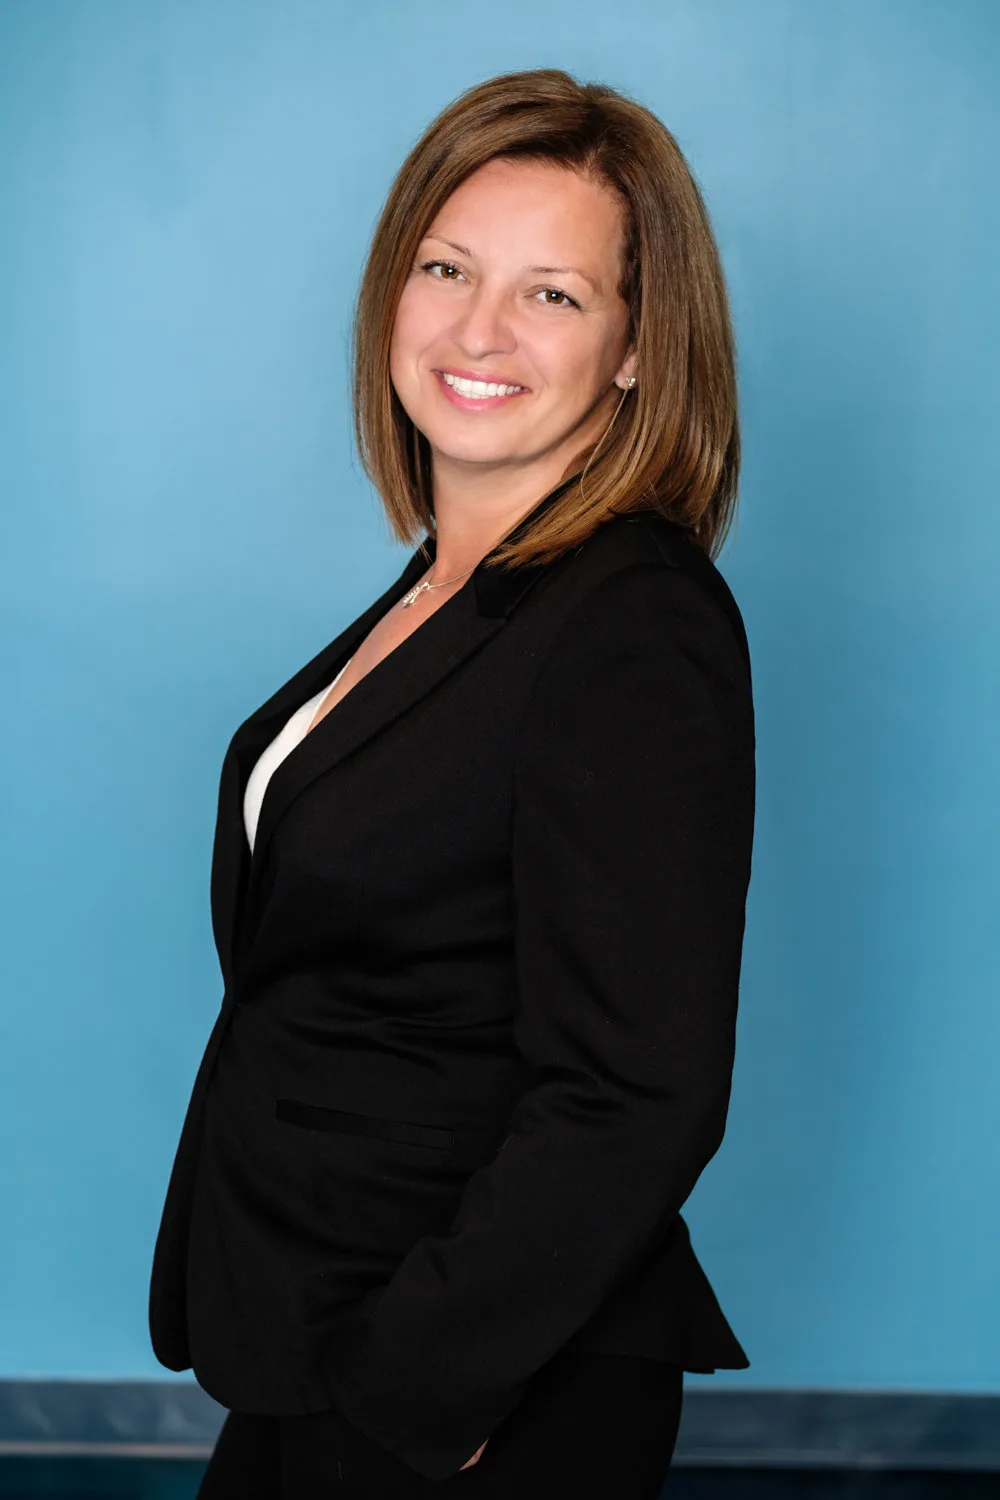
First-time buyers, renewals, refinances, bruised credit & self-employed files across Halton Region
One Local Broker for Every Stage in Oakville
Oakville is an expensive place to buy and a very easy place to love. Downtown Oakville is one of my favourite places to spend an afternoon, the stretch along Lakeshore down to the harbour, and Bronte has its own version of the same thing at the other end of town. What that costs you is a median price well north of a million dollars, which changes the mortgage conversation completely. Bigger files, more scrutiny, and a lot of income that doesn't arrive as a paycheque. Oakville's median household income runs around $155,000 against roughly $102,000 for Ontario, and a good share of that is business income rather than salary. Banks are worse at reading business income than they think. Here's where I do the most good.
First-Time Home Buyers
Oakville is a serious first purchase. A real pre-approval, an honest budget at this price point, and every first-time program you qualify for.
FHSA, RRSP & land transfer rebate →Renewals & Refinances
Your renewal letter is not your best offer, and on an Oakville-sized mortgage the gap is real money. I shop your rate at renewal and pull equity when it makes sense.
Don't auto-sign the bank's offer →Self-Employed & Complex Files
The work other brokers find too messy. Business income, dividends, write-offs, bruised credit, a past decline. This is my specialty, not my exception.
Stated income & alt-lender options →Buying Your First Home in a Million-Dollar Market
Here's the honest math. Oakville's median sale price was around $1.2 million in August 2026, and the market carried roughly six months of inventory with homes averaging 40 days to sell. That's a buyer's market, which matters more than most people realise. It means time to arrange financing properly, room to keep a condition on your offer, and less pressure to waive something you shouldn't. At this price, the gap between the best and worst lender on your file is measured in tens of thousands of dollars over a single term.
Get the order right, and it starts with a plan, not a listing:
- A pre-approval that locks your rate for up to 120 days while you shop
- The First Home Savings Account (FHSA) and the RRSP Home Buyers' Plan, used together where it helps
- Ontario's land transfer tax rebate for first-time buyers, worth up to $4,000
- An honest read on your real budget, closing costs included, not just the maximum a lender will hand you
- The commute trade-off, if you're weighing Oakville's price against time on the road or the GO line
Want the full walk-through? I broke down every step from offer to approval in this guide to the mortgage process. And if you're also looking at the bigger Georgetown market, here's my Georgetown mortgage broker page.
"Your first mortgage sets the tone for the next twenty years. Get it right once."— Kat Brazier, Mortgage Agent Level 2, FSRA #M23007671
- A plain-language pre-approval before you tour a single home
- Rate held while you shop, so a rate hike can't derail your budget
- Every rebate and program you qualify for, mapped out up front
- Someone who picks up the phone on closing day
Oakville Equity, and What It Can Actually Do
Oakville homes carry more equity than almost anywhere else in Halton, and most owners underuse it. People here tend to think of a refinance as something you do when you are stuck. In practice it is more often the cheapest way to fund the next thing, whether that is a second property, a business, tuition, or clearing debt that is costing you three times as much.
A renewal or refinance is the easiest time of your whole mortgage to win, here's what I look at:
- Whether switching lenders at renewal beats your current offer, because at this mortgage size a small rate gap is real money
- Refinancing to release equity for a second property, a business, or a renovation
- A refinance compared honestly against a HELOC, so you choose with the full picture
- How business or dividend income is read by different lenders, which changes what you qualify for
Start about 120 days before maturity. That's the window to lock a rate and switch with zero rush. Curious whether to stay or go? Here's how a broker and a bank actually differ at renewal, and the case for refinancing to clear credit card debt.
"The bank's renewal letter is a test. Most people pass it by doing nothing, and pay for it for five years."— Kat Brazier, Mortgage Agent Level 2, FSRA #M23007671
- I compare your renewal against 50+ lenders, not just your current one
- Switch deals where the new lender covers most of the moving costs
- Refinance options to turn home equity into breathing room
- A reminder before your window opens, so you're never rushed
Banks Have a Box. You Don't Fit in It.
If you're self-employed, your bank sees write-offs, fluctuating income, and missing T4s. They run your NOA through a formula. When the number comes back low, you get declined. The problem isn't your income. It's their process. And a single bank branch only has one process.
Here's what banks flag on self-employed and complex files:
- Your Notice of Assessment income is lower than your real earnings due to legitimate write-offs
- You're incorporated and pay yourself through dividends rather than a salary
- You've been self-employed for under 2 years
- Your income varies year over year, even if the trend is upward
- A past decline, bruised credit, or CRA arrears in the picture
These are not red flags. They're signs of a real, working life. I place these files with lenders who get it. If a bank has already turned you down, that's usually where I come in, see real declined files I turned into approvals on The Bank Said No.
"I don't sell products. I solve problems. The files banks call complicated are the ones I do best."Kat Brazier, Mortgage Agent Level 2, FSRA #M23007671
- Stated income programs that use gross revenue, not your NOA
- Bank statement mortgages for clients with strong cash flow
- Alt-A and alternative lenders for complex income structures
- Private lending options when timing matters more than rate
How Oakville Business Income Actually Gets Read
Oakville has an unusually high share of households whose money comes from a business rather than a paycheque. Median household income here runs around $155,000 against roughly $102,000 for Ontario, and a good part of that gap is business income. Banks are worse at reading it than they think.
Where a strong earner ends up with a weak number:
- Your Notice of Assessment shows what you paid yourself, not what the business earned, and legitimate write-offs cut it further
- If you pay yourself in dividends, some lenders gross them up and some do not, which changes your qualifying income materially
- Retained earnings inside a corporation are often ignored entirely, even when the company is plainly healthy
- Two strong years and one soft year usually gets averaged, and the average is what you qualify on
- A rental or second property in the mix can help or hurt, depending on how that lender treats rental offsets
The same file, sent to three lenders, can come back with qualifying incomes that differ by six figures. That is not a rounding error, and on an Oakville-sized purchase it decides whether the deal happens at all.
Oakville, Georgetown & Across Halton
First homes, long-time owners, business owners and commuters. If you live or are buying around Oakville, there's a good chance I've placed a file like yours.
First-Time Buyers
Using Oakville as your foot in the door to Halton Region. Real pre-approval, FHSA and rebate planning, and a budget you can actually live with.
First purchase at this price →GO & Highway Commuters
Oakville, Bronte and Clarkson GO all sit on the Lakeshore West line, with the QEW and 403 alongside. You are paying for that access, so it is worth knowing what it is actually worth to you.
Lakeshore West & QEW →Self-Employed & Business Owners
Incorporated, sole proprietor, trades or commission. Your write-offs shrink your paper income. I find lenders who use what you really earn.
Stated income & alt-doc →Established & Century-Home Owners
Oakville's older housing stock builds real equity. I help you refinance for a renovation, a new roof, or to consolidate debt into one lower payment.
Refinance & renovation →Renewals Coming Up
Your renewal letter is not your best offer. I compare your rate against 50+ lenders before you sign, often with the new lender covering switch costs.
Don't auto-sign the bank →Already Declined by a Bank
A no from the branch is a starting point, not a verdict. Self-employed, bruised credit, CRA debt or a complex file. I find the lender that says yes.
Where most of my files start →One Bank Has One Answer. I Have Fifty.
When you walk into your bank, they're deciding whether you fit their box. When you call me, I'm deciding which lender's box you fit best, while shopping your rate at the same time.
50+Lenders competed for your mortgage
Get started| What matters to you | Your bank | Kat Brazier |
|---|---|---|
| Lenders compared | 1 | 50+ |
| First-time buyer programs | Some | All you qualify for |
| Shops your renewal rate | No | Yes |
| Self-employed expertise | Limited | Specialist |
| Works for your interests | Works for the bank | Works for you |
Three Steps to a Mortgage That Actually Fits
No paperwork marathon on day one. We start with a conversation. I'll tell you upfront what's realistic before you commit to anything.
Free Discovery Call
We talk through your situation: your goals, your budget, your timeline, any previous declines. I'll give you a straight read on your options. No commitment, no fluff.
I Shop Your File
I take your file to the lenders most likely to approve it. Not every lender, but the right ones. One application, multiple lenders, single credit pull. I bring back the best terms.
You Get Approved
I walk you through the offer, the conditions, and what to expect at closing. I stay on file until the mortgage funds. I'm available if anything comes up.
Oakville Mortgage Questions I Hear Every Week
Real questions from Oakville buyers, homeowners, and business owners.
What does it cost to buy in Oakville right now?
Oakville's median sale price was around $1.2 million in August 2026. The market carried about six months of inventory and homes averaged 40 days on market, which is a buyer's market rather than a seller's. Practically that means you have time to arrange financing properly instead of waiving conditions to win a bidding war. I'll run your real numbers before you start looking.
Can I get a mortgage in Oakville with bad credit?
Usually yes. A low score narrows which lenders will look at your file, it does not close the door. Credit unions, B-lenders and private lenders all work with bruised credit and price it very differently, so the same file can come back with offers that are far apart. If you already own in Oakville, the equity in the home often matters more to those lenders than the score does.
I'm self-employed in Oakville. Will a bank count my real income?
Often not the way you'd expect. Banks read your write-offs and your Notice of Assessment and see a low number, which is a problem in a town with as many business owners as this one. I work with lenders who use gross revenue, bank statements, or stated-income programs, so your actual earning power counts. Self-employed and complex files are my specialty, not my exception.
I'm renewing my Oakville mortgage. Should I just sign the bank's letter?
Not before you compare it. On a mortgage this size a small rate difference compounds into real money over a five-year term. About 120 days before your maturity date I compare your renewal against 50+ lenders and check whether switching beats staying, often with the new lender covering most of the switch costs.
Can I refinance to pull equity out of an Oakville home?
Frequently, yes, and the equity here tends to be substantial. People use it for a renovation, a second property, tuition, or to clear higher-interest debt into one lower payment. I'll show you what a refinance looks like against a HELOC so you can choose with the full picture rather than taking whichever one your bank happens to sell.
Are you local to Oakville?
I'm a Halton mortgage agent working across Oakville, Burlington, Milton and Halton Region, and my brokerage is based in Burlington just down the QEW. Downtown Oakville is somewhere I spend time by choice, not only for work. You get someone who knows the area and actually picks up the phone.
My bank declined me. Does that mean I can't buy in Oakville?
No. It means that bank's policy didn't fit your file. A decline tells you about one lender's box, not about whether the mortgage is possible. The useful first step is finding out exactly why, because a credit reason, an income reason and a property reason each need a different fix. From there it's a question of which of the fifty-odd lenders I work with fits.
Explore How I Help in Oakville
Oakville pulls in first-time buyers and long-time owners in equal measure, and the files that need a broker most are the ones a bank won't bend for. If you're self-employed, you've been turned down, or you're sitting on equity in a complex or older property, that's my lane. I also work with real estate investors, families navigating separation or divorce, and homeowners who've fallen behind on payments.
Let's Talk About Your File
No pressure, no obligation. Tell me your situation and I'll tell you what's possible, usually within 24 hours. If I can help, we'll move forward. If I can't, I'll tell you that too.
- 416-464-6763
- info@katbrazier.com
- Oakville, Burlington & Halton Region, Ontario
Kat Brazier, Mortgage Agent Level 2
FSRA License #M23007671
Book a Free Discovery Call
Tell me about your situation. I'll respond within 24 hours.
Message received. Thank you!
I'll review your situation and be back to you within 24 hours. Check your inbox (and spam, just in case).
Your information is never shared. By submitting this form you agree to our Privacy Policy.